

Portfolio Turnover - What is it? How to calculate?
Article last updated: September 10, 2026
Portfolio turnover is the measure of how much trading a portfolio actually did. It is quoted by every mutual fund and ETF, it is rarely calculated by individual investors, and it is one of the more reliable predictors of what a portfolio will cost to run. This guide covers what portfolio turnover is, how it is calculated, what it costs you, and what a reasonable ratio looks like.
Key takeaways
- Portfolio turnover is a metric that measures how frequently the investments within a portfolio are bought and sold over a period, usually 12 months.
- Portfolio turnover is calculated as the lesser of total purchases or total sales during the period, divided by the average value of the portfolio over that same period.
- A portfolio turnover of 100% means the portfolio traded an amount equal to its entire average value during the period; 0% means nothing was bought or sold.
- High portfolio turnover raises costs in two ways: transaction fees and spreads on every trade, and capital gains tax realised earlier than it needed to be.
- Long-term investors typically run portfolio turnover below 10%, while active traders can exceed 100% in a single year.
What is portfolio turnover?
Portfolio turnover is a metric that measures how frequently the investments within a portfolio are bought and sold over a specific period, expressed as a percentage of the portfolio's average value. It is usually measured on a 12-month basis.
A high turnover rate indicates frequent trading activity, while a low turnover rate implies a more passive investment approach. A long-term investor will usually have far lower portfolio turnover than a day trader does.
Portfolio turnover is a measure of activity, not of skill. A 5% turnover ratio does not by itself mean a portfolio performed well, and a 150% ratio does not mean it performed badly. What turnover reliably predicts is cost.
How do you calculate portfolio turnover?
Portfolio turnover is calculated by taking the lesser of the total value of assets bought or the total value of assets sold during a period, and dividing it by the average value of the portfolio over that same period.
Portfolio Turnover = min(Total Purchases, Total Sales) / Average Portfolio Value
Portfolio Turnover Formula:
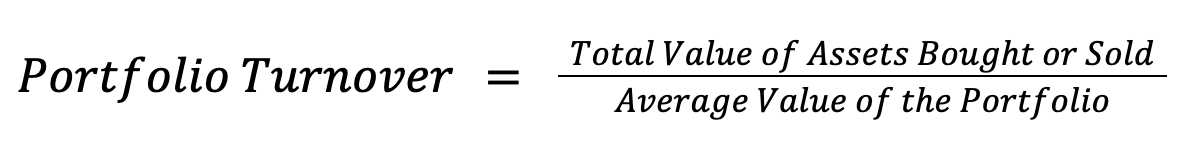
Where:
- Total Value of Assets Bought or Sold = the total value of assets bought, or the total value of assets sold, within the period — whichever is less.
- Average Portfolio Value = the average market value of the portfolio across the period, commonly the average of monthly values, or simply the average of the starting and ending values for a rough figure.
Taking the lesser of purchases and sales is the point of the convention, and it is what stops the ratio from misreading growth as trading. An investor who deposits new cash and buys with it has made purchases but no sales, so the lesser figure is zero and turnover is zero — which is correct, because nothing was actually turned over. The same logic keeps a large withdrawal from inflating the ratio.
Portfolio turnover calculation example
A portfolio that bought $60,000 and sold $45,000 of assets over a year, while averaging $200,000 in value, has a portfolio turnover of 22.5%.
Work through the portfolio turnover formula, which is the lesser of purchases or sales divided by the average portfolio value:
Average Portfolio Value = ($180,000 start + $220,000 end) / 2 = $200,000

min(Purchases $60,000, Sales $45,000) = $45,000

Portfolio Turnover = $45,000 / $200,000 = 22.5%
A 22.5% turnover means roughly a fifth of the portfolio was replaced during the year, which implies an average holding period of a little over four years.
Compare that with a buy-and-hold investor who put $20,000 of new savings to work during the year and sold nothing. Purchases are $20,000 and sales are $0, so the lesser figure is $0 and portfolio turnover is 0%, no matter how much was deposited.
What does portfolio turnover mean to investors?
Portfolio turnover matters to investors because every unit of turnover carries a cost, in transaction fees and in tax paid earlier than necessary. The higher the portfolio turnover, the more of the return is consumed before it reaches you.
The transaction cost side is obvious: every trade carries a commission, a bid-ask spread and sometimes exchange or currency fees. Trade twice as often and you pay those twice as often.
The tax side is less visible and usually larger. Realising a gain every period, instead of deferring it, means the tax is paid out of capital that would otherwise have kept compounding. Charlie Munger illustrated the effect:
"If you're going to buy something which compounds for 30 years at 15% per annum and you pay one 35% tax at the very end, the way that works out is that after taxes, you keep 13.3% per annum. In contrast, if you bought the same investment, but had to pay taxes every year of 35% out of the 15% that you earned, then your return would be 15% minus 35% of 15%-or only 9.75% per year compounded. So the difference there is over 3.5%. And what 3.5% does to the numbers over long holding periods like 30 years is truly eye-opening."
How much of a difference does 3.5% a year make? Starting with $10,000 and compounding at 9.75% for 30 years — the after-tax rate when the tax is paid annually — leaves $162,981. Compounding at 15% and paying the 35% tax once at the end leaves $430,377. That is 2.64 times as much money, from the same investment and the same tax rate, purely because the tax was deferred.
This is why turnover interacts with how cost basis is tracked: the method you use to decide which shares were sold determines how large a gain each sale realises, and therefore how expensive a given level of turnover turns out to be.
What's a good portfolio turnover ratio?
A good portfolio turnover ratio for a long-term investor is under 10%, and for many buy-and-hold investors it is close to 0%. Turnover should be judged against the strategy: given the same strategy and return profile, the portfolio with lower turnover is preferable because its transaction costs and tax drag are lower.
| Turnover ratio | What it implies | Typical of |
|---|---|---|
| 0% - 10% | Average holding period of a decade or more | Long-term buy-and-hold investors, index funds |
| 10% - 50% | Positions held roughly 2 to 10 years | Patient active managers, periodic rebalancers |
| 50% - 100% | Positions held around 1 to 2 years | Actively managed funds |
| Over 100% | The whole portfolio replaced within a year | Short-term and tactical trading strategies |
Terry Smith's Fundsmith is a well-known example of a deliberately low-turnover fund, with turnover rates most of the time between 2-5% and 11.1% in 2023.
Charlie Munger famously stated, "Investing is where you find a few great companies and then sit on your ass," highlighting the value of patience and conviction in long-term investing. Terry Smith states a similar philosophy — "Buy good companies. Don't overpay. Do nothing." — and is committed enough to the "Do nothing" part that he tracks and discloses the fund's portfolio turnover every year.
What raises portfolio turnover without you deciding to trade?
Portfolio turnover rises from routine portfolio maintenance as well as from deliberate trading, and rebalancing is the most common source. Four causes account for most unintended turnover.
- Rebalancing. Returning a portfolio to its target asset allocation means selling what has grown and buying what has lagged, which is turnover by definition.
- Position trimming. Cutting a holding back when its portfolio weight drifts past a limit produces sales in the strongest positions, which are also the ones carrying the largest unrealised gains.
- Corporate actions. Mergers, buyouts and index reconstitutions force sales you did not choose.
- Fund switching. Moving from one fund to a cheaper equivalent is a single decision that turns over the entire position at once.
None of these is a reason to avoid rebalancing, which manages real risk. The point is to count the cost: rebalancing annually rather than quarterly achieves most of the same risk control at a fraction of the turnover.
Frequently asked questions
What does a 100% portfolio turnover ratio mean?
A portfolio turnover ratio of 100% means the portfolio bought and sold an amount equal to its entire average value during the period. It does not mean every single holding was replaced — a small number of positions traded repeatedly can produce the same figure. As a rough guide, 100% turnover implies an average holding period of about one year.
Where can I find a fund's portfolio turnover ratio?
A fund's portfolio turnover ratio is disclosed in its prospectus and annual report, usually in the financial highlights table alongside the expense ratio. It is worth reading next to the expense ratio rather than instead of it, because turnover-driven trading costs and tax are real expenses that the stated expense ratio does not include.
Is high portfolio turnover always bad?
No. High portfolio turnover is a cost, not a mistake, and some strategies genuinely require it — short-term trading, tactical allocation and certain arbitrage approaches cannot work without it. The question is whether the strategy earns enough extra return to cover the fees, spreads and earlier tax that the turnover creates. Most do not.
Does portfolio turnover matter inside a tax-sheltered account?
Portfolio turnover matters less inside a tax-sheltered account such as an IRA or ISA, because gains are not taxed as they are realised, removing the larger of the two costs. Transaction fees and bid-ask spreads still apply on every trade, so high turnover still erodes returns — just more slowly than in a taxable account.
How to track your trading activity in Portseido
Portseido keeps the transaction record that a portfolio turnover calculation is built from. It consolidates holdings across multiple brokers and multiple currencies into one portfolio, stores every buy and sell with its date and value, tracks cost basis so you can see the gain each sale realises, and reports dividends, yield on cost, allocation and time-weighted and money-weighted returns. Transactions can be imported directly from brokers or from a CSV, so the history stays complete without manual entry.
Portseido does not calculate the turnover ratio itself, and it tracks and reports on your portfolio rather than giving buy or sell recommendations. What it gives you is the purchases, sales and portfolio values in one place, which is the part most investors cannot assemble when their accounts are spread across brokers. There is a free plan, and paid features come with a 14-day trial that does not need a credit card. Try Portseido free
Great further reads:
- Investing for growth by Terry Smith
- Poor Charlie's Almanack by Charles T. Munger